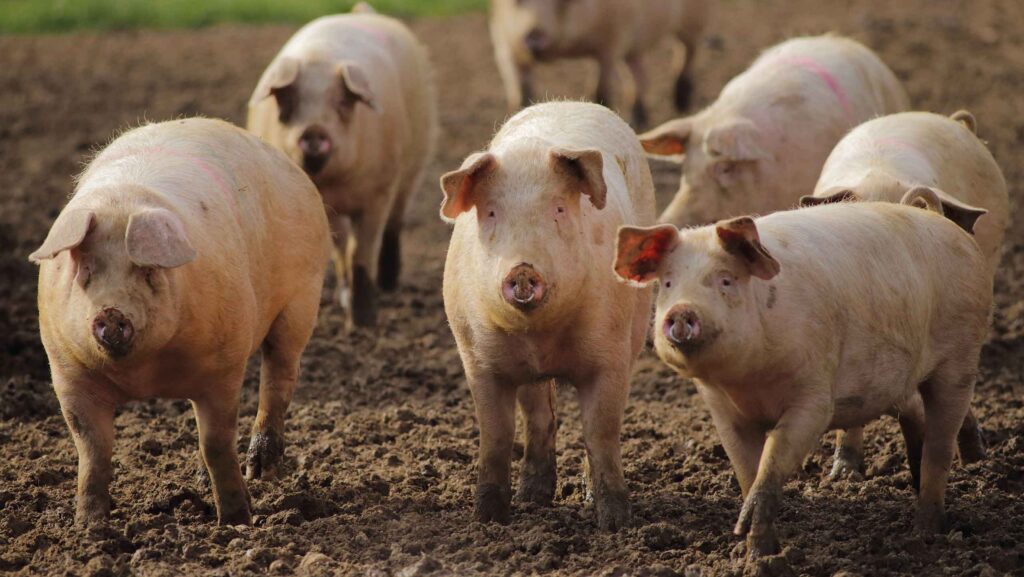
The introduction of the Fair Dealing Obligations (Pigs) (FDOP) regulations was meant to restore fairness and balance to the supply chain – and, over time, they will hopefully do just that, setting out a framework for pig contracts and clear rules that must govern them.
But the timing of the full introduction of the regulations in mid-August, and the need to renegotiate written contracts to be compliant, could hardly have come at a worse time for pig producers.
It coincided with a period of supply- demand imbalance and low EU and UK prices, and as the big processors, for varying reasons and to different extents, have been looking the realign and generally reduce their pig supply base.
In the months leading up to the implementation of the regulations, many producers had contracts terminated – although processors have denied there was a link.
Writing for the Tribune, industry analyst Mick Sloyan said: “Many were then offered new contracts that reduced contracted numbers or reduced prices, or both. It was also reported that many producers were not offered a contract and so are being forced to sell on the spot market,” he said.
The concerns of producers were highlighted in the September issue of Pig World. Nottinghamshire producer Fred Allen said he felt ‘backed into a corner’ after processors left it ‘incredibly late to put contracts in front of producers’.
“I need somewhere to sell my pigs. If I want to guarantee an outlet, I had to sign a contract by the end of August, even if I’m not entirely happy with what I’m being offered. That doesn’t feel like a particularly strong negotiating position for a farmer,”
he said.
A survey of NPA members in the run-up to the deadline for compliance showed that only 6% had an FDOP-compliant contract in place. Nearly two-thirds were aware of the regulations but did not have a contract in place, and 22% said they were ‘not very aware’ of FDOP and had not discussed it with their customer.
Adjudicator
The FDOP regulations are overseen by the Agricultural Supply Chain Adjudicator (ASCA), Richard Thompson. While expectations need to be managed about exactly how much ASCA can do to address producers’ immediate concerns, Mr Thompson and his office are certainly making every effort to engage with the industry.
In early September, eight independent pig producers, who had all been given notice on at least a proportion of their pigs by their processor, set out their plight to ASCA and Defra officials at a roundtable event organised by the NPA.
It highlighted numerous issues over how new pig contracts have been formulated and negotiated over the summer to comply with the FDOP regulations.
In some cases, the contracts being offered were convoluted and unappealing to the producers, who felt they had nowhere else to go in the current marketplace. Producers also spoke about how long the process was taking, including getting sight of the contract in the first place, and about poor communication from the processors.
Some producers highlighted the extremely low prices they are receiving as a result of having to sell on the spot market, and the heavy losses they are enduring, with some reducing their herd size as a result and one getting out of pigs altogether.
A few weeks later, a representative from the ASCA office addressed the NPA’s Pig Industry Group, urging anyone who has queries about the implementation of the regulations to get in touch with it.
He explained how experience with the dairy regulations showed the ‘success of good faith early engagement’ to address issues before they became more serious.
“My key message today is that our office is really keen to chat. If in doubt, please get in touch – it is entirely free and anyone can contact us at any time,” he said.
“We are trying to foster good relations with the industry and our experience with the dairy sector shows that where you get the engagement, it will often remove the need for a formal complaint.”
He said the key challenge was making people aware of how to contact ASCA, and outlined the two main routes:
- The ASCA office’s main email is: asca@defra.gov.uk
- There is also an ‘in confidence’ email address: asca-in-confidence@defra.gov.uk
Price transparency
While there is no doubting ASCA’s willingness to engage to be proactive, addressing ongoing problems – for example, over price transparency – will not be straightforward, according to Mr Sloyan, who addressed the contentious issue of processor ‘shout prices’ in a recent Tribune article.
Shout prices are often included in pricing formulas, for example alongside the SPP and an element of cost of production.
While the justification for the shout price is often to inject ‘some dynamism into the weekly price and reduce the drag effect of using an SPP’, many producers believe they are set ‘with the sole objective of getting pig prices down quickly when the market is under pressure’, Mr Sloyan said.
Indeed, producers have, in recent months, reported some very low shout prices that have dragged their overall pig price to levels way below the SPP. “The problem is that shout prices lack transparency in the way they are determined,” he added.
The FDOP regulations seek to address this, requiring the way variable prices are determined and the factors used by the purchaser in calculating the price to be set out in the contract and agreed by both the purchaser and seller. “The expectation in the regulations is that the processor will clearly state the factors that determine the shout price. It will not be sufficient to just say, ‘this is the shout price – take it or leave it’,” Mr Sloyan said.
However, the onus is on the seller to initiate the process and request a written explanation from the buyer every time the price is determined. The processor then has seven days to provide an explanation.
Where variable prices are used, the contract must include a third-party verification procedure, enabling sellers to refer an explanation given by the processor to an independent person, the cost of which can be shared. However, the biggest barrier, according to Mr Sloyan, might be an unwillingness among producers to go down that route, partly for fear of the longer-term consequences.
Under FDOP, the need for explanations and third-party verification is removed if at least 97.5% of the price is determined by publicly or mutually available data, for example, the SPP or a cost-of-production-based formula.
SPP transparency
The current situation has generated a vast range of prices received, depending on a mix of previous contracts negotiated, foresight and, in some cases, a bit of luck.
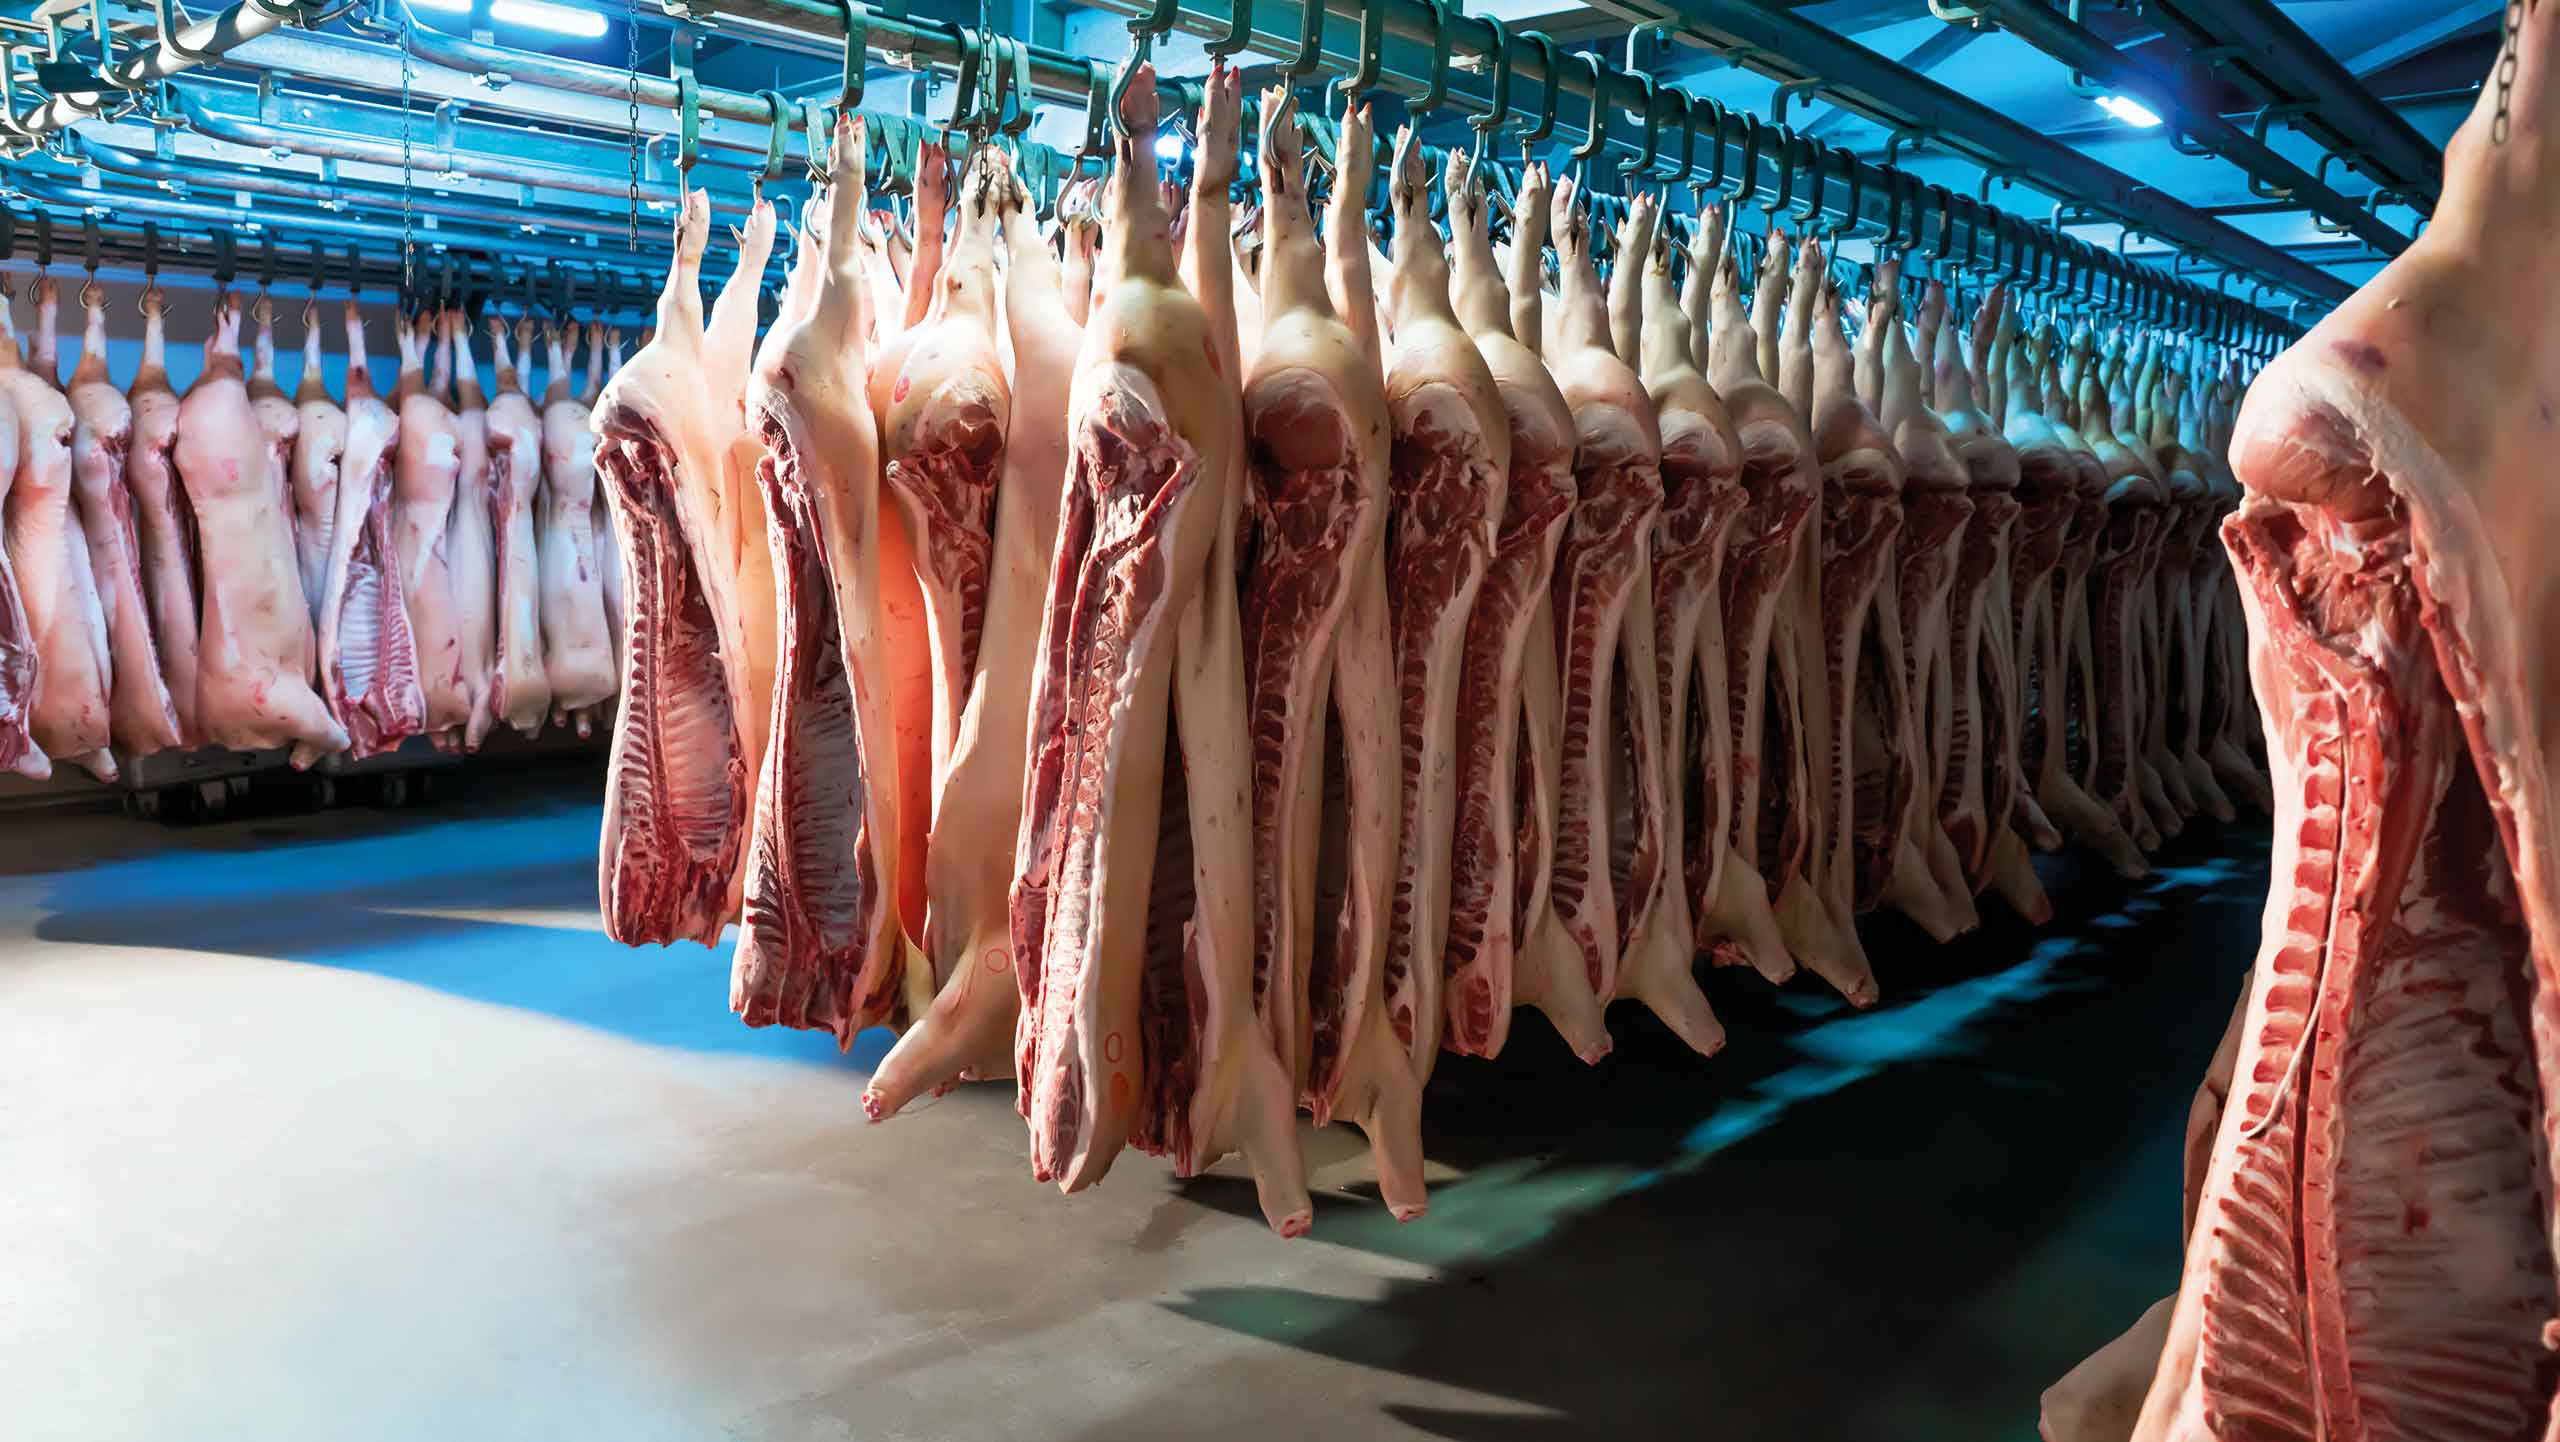
The SPP, the average weekly price by abattoirs for ‘standard’ pigs – excluding outdoor-bred and free-range – has been steady at about 178-180p/kg since the spring. But within that, some producers are reporting prices in the 130-150p/kg range, particularly when forced to sell ‘distress pigs’ on the spot market. Others who have not had contracts cut and are on healthy long-term cost-of-production-linked contracts are receiving comfortably above that average, in some cases around the £2/kg mark.
This is a cause of angst for some producers receiving those low prices, who feel the published SPP doesn’t reflect what is happening at the edges of the market.
“Monitoring this shift in the market is vital for everybody in the production and processing chain,” Mr Sloyan said. “The problem is that the current dynamics in pig pricing are not transparent enough.
“And without transparency it is not possible to have a fully functional, efficient and competitive market, which is bad for everyone, including consumers.”
AHDB already publishes the average price of pigs by 10kg weight bands using the SPP data. This could be enhanced by also producing the distribution of prices in 5p or 10p ranges, Mr Sloyan suggested.
“For example, a narrowing of the distribution of prices could indicate a strengthening market while a spike in particularly low prices could indicate an abuse of market power,” he said.
He stressed that enhanced reporting of prices needs to be done in a way that conforms with competition law and, in general, this is more likely to happen if something is covered by statute.
“So, it might be better for AHDB to use the reference price data, which is not only mandatory, but covers the whole market, rather than the SPP data, which is voluntary and only covers part of the market,” he said. “While better market information won’t necessarily improve the price, it might just help everyone navigate difficult times a little more easily.”
AHDB pork sector director Mark Haighton said the levy body recognises the importance of transparent, reliable pig-price reporting, particularly when market conditions and contractual arrangements are changing.
“The SPP remains an independently calculated and validated measure based on actual transactions, but, as an average, it currently does not provide visibility on the full distribution of prices being paid. We recognise the limitations of a single published average, particularly when some independent producers are currently being offered prices significantly below the published SPP,” he said.
“AHDB is committed to continuously improving the information we publish. Feedback from several stakeholders has highlighted that publishing additional information on the distribution of prices within the overall SPP population would give the industry a clearer and more complete understanding of the market. We are, therefore, in the process of investigating whether this is something we can take forward.
“Any information we publish must meet our standards for data quality, protect the confidentiality of individual businesses and comply fully with our obligations under competition law.”
Forecasting
The situation has also, once again, highlighted the need for better forecasting. In its proposed support package to Defra, the NPA is suggesting using the powers within the Agricultural Act to gather data to improve forecasting for the British breeding herd, including piglets born.
There is an existing precedent within the poultry sector, whereby collated chick placement numbers are published on a monthly basis, which the poultry sector uses to provide an overview of the current market. The number of eggs set is also published, offering an accurate indication of future supply. This data is considered very useful and is widely used by the sector, the NPA said.
AHDB is also ‘actively exploring’ proposals to strengthen the data available for market analysis and forecasting
The NPA stressed that, for the forecasting data to be industry-wide, including independent producers, and ‘accurate and meaningful’, it would potentially need to be mandated. It suggested that data powers within the Agricultural Act would provide a suitable instrument to deliver a more accurate and meaningful outcome, noting that the provision of forecasting was originally intended to be included as part of the FDOP regulations.
Autumn is looking ‘extremely challenging’
It has already been another tough year, and with potentially about 12,000 uncontracted pigs set to come onto the market each week from October, as contracts expire, a difficult few months lies ahead for some.
“The outlook heading into the autumn is extremely challenging,” said NPA Pig Industry Group (PIG) chair Joe Dewhirst.
“Affected producers face considerable uncertainty, alongside continued pressure from rising feed costs, limited processing options and the risk of weaker prices. The effect will vary between businesses, but independent producers with contracts expiring will be most exposed.”
Mr Dewhirst, who is joint managing director at Yorkwold Pig Pro, said the situation also raises important longer-term questions about the structure and resilience of the British pig industry.
“If independent producers are forced to reduce numbers or leave the sector, the balance could shift further towards larger, vertically integrated businesses,” he said.
“A healthy industry needs a diverse producer base, fair and transparent trading relationships and sufficient processing capacity. Greater certainty and stronger collaboration across the supply chain will be essential if producers are to plan, invest and maintain confidence.”
NI troubles
Pig producers in Northern Ireland were rocked earlier this year, after an estimated 35-40 suppliers to Sofina were given notice for some or all of their pigs by Sofina Foods. Many of these cuts are set to come into effect in the autumn.
Ulster Farmers’ Union deputy president Clement Lynch said: “There remains significant concern among some of our pig members about the current market situation, particularly around Republic of Ireland pigs continuing to come into the Sofina factory. We have requested a further meeting with Sofina to discuss these concerns directly.
“Confidence varies across the sector, with some farms in a stronger position than others. However, what our producers need is certainty and a clear commitment from across the supply chain to support UK-produced, Red Tractor-assured pigs.
“Our farmers are producing to high standards and need confidence that this will be recognised in processing and sourcing decisions. Maintaining a strong domestic pig sector requires processors and retailers to back our producers and provide the stability they need to plan and invest for the future.”
Commenting to Pig World about the situation in the summer, Graham Wilkinson, Sofina’s group agriculture director, said the decision not to renew ‘a number of NI pig supply contracts’ was ‘entirely driven by the ongoing global volatility, pricing pressure and shifting customer demands, which continue to challenge the British and Irish pig sector’.
Scotland woes
Nowhere has been hit harder than Scotland, where contract notices and some extremely low prices have seen a further contraction of the pig sector.
In his regular column in this issue, Scottish producer Dennis Bridgeford said the prospect of many producers trying to find outlets for non-contract pigs this autumn is a ‘horrendous thought that will no doubt have ramifications for all independents’.
He said the critical mass of the Scottish industry was ‘almost gone’. “Over the next few months, there are going to be some seriously hard financial decision made.”