Pig producers endured losses of, on average, £25 per slaughter pig during the third quarter of 2026, as feed costs soared, according to the latest AHDB estimates.
The estimates, using performance figures for breeding and finishing herds, indicate that the full economic cost of production increased by 6p from Q2 to stand at 207p/kg deadweight.
Feed costs increased by around 5p to 124p/kg, continuing to make up 60% of total costs. Variable costs increased by 1p due to higher energy and fuel costs, while labour costs also edged up.
Pig prices, as measured by the SPP, averaged 180p/kg over Q3, an increase of 1p/kg on Q2. This resulted in margins per slaughter pig of -27.4p/kg deadweight, which equated to -£24.95 per pig, compared with an average net loss of £20/pig in Q2 and £4/pig in Q3. This followed a period of 10 positive average net margins in 11 quarters.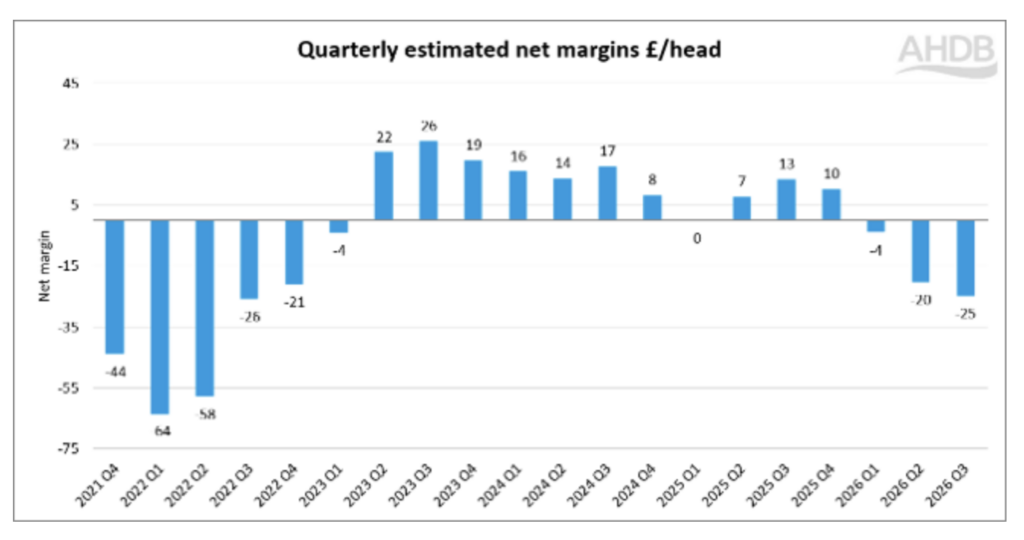 These headline are just averages. The market struggles the pig sector has endured this year have been characterised by a wide range of prices received, with many producers selling pigs for significantly below the Q3 SPP average of 180p/kg. With costs also varying significantly, some producers will be suffering much bigger losses than the quarterly average, while others will have fared relatively well.
Moving into Q3, after being steady during September, the SPP fell to 176.45p/kg by the end of October, further pressurising margins, although wheat prices have also fallen, which should result in a slight easing of feed costs.